Texas Muniment of Title
If a bank told you an account is frozen and didn't explain what that actually means, you're not stuck, and you're not the only one this has happened to. A probate attorney would typically charge $1,500–$3,500 to walk you through exactly what Texas law already lets you do yourself. This guide is $37, one-time, and covers the same ground — the eligibility rule, the official form, and what to say if a bank or clerk pushes back.
If a title company or a buyer just told you a house can't be sold or refinanced until 'the will gets probated,' this is usually the fast path to fixing that. Texas's Muniment of Title (Estates Code Chapter 257) lets an heir use a deceased person's valid will — once admitted to probate by a court — as the legal record of ownership, without appointing an executor or opening a full estate administration. There's no dollar cap, unlike the Small Estate Affidavit, but it only works when a valid will exists and the estate has no debts beyond a home-secured lien (an ordinary mortgage doesn't disqualify it). A typical uncontested filing runs $1,500–$3,500 in attorney fees, well under general probate rates, plus a mandatory 10-day citation-posting period before a hearing can even be set. This is informational only — not legal advice — and does not draft, file, or individualize anything for you.
Last reviewed
Not sure this is the right page? It comes down to one fact: did the person who died leave a valid will? If not, you likely want the Small Estate Affidavit guide instead → . Settling both a bank account and a house from the same estate? You may need both guides — see the FAQ below.
- Built on the statutory requirements, not a guess
- Every claim cited to Estates Code Chapter 257
- Secure checkout by Stripe
- Money-back if the filing is rejected
Splitting up the estate with someone else? Send them this page before you start.
Why timing matters: Texas requires the probate application — muniment of title included — to be filed within four years of the date of death. Courts take a genuinely liberal view of the exception (not realizing a will existed, or not knowing probate was required, is usually enough), but proving it means the court must appoint an attorney ad litem for unknown heirs, adding real time and cost. Families who don't realize probate is needed until a title company or buyer flags it years later can still usually qualify — but the closer to four years, the more this is worth getting in front of an attorney promptly rather than waiting further.
Texas's Muniment of Title — no dollar cap
Texas's Muniment of Title has no dollar ceiling — eligibility instead turns on the specific conditions Estates Code Chapter 257 sets out. There's no total to add up before you know whether it applies. Muniment of Title is filed with the court, not handed directly to a bank or DMV. Texas does not publish a fill-in form for this mechanism — see the how-to-file guide below for what the statute requires instead.
How to file, step by step
- 1
Confirm a valid will exists and names the estate's property clearly
Muniment of Title works by using the court-approved will itself as the record of who owns what — there must be a valid will, and it should clearly identify the property being transferred (most often real estate, but it can include other titled assets like vehicles and financial accounts).
- 2
Confirm there are no debts other than a home-secured lien
Beyond a mortgage or other lien secured by real property, the estate should have no other outstanding debts. Unresolved credit card debt, medical bills, or other unsecured creditor claims typically make this the wrong mechanism.
- 3
File within four years of the date of death
Texas generally bars probate applications (muniment of title included) filed more than four years after death, with narrow exceptions. This is one of the most consequential, least-understood deadlines in Texas probate — confirm your timeline early.
- 4
File an application to probate the will as a muniment of title with the county probate court
This is a court filing, not a form presented directly to a bank — you (or your attorney) file an application asking the court to admit the will to probate specifically as a muniment of title, rather than appointing an independent executor. Once filed, the county clerk issues a citation that must be posted at the courthouse for 10 days before a hearing can be set — a hard floor on the timeline that applies regardless of how quickly everything else comes together.
- 5
Attend the required court hearing and sign the required affidavits
At the hearing, you (or another witness, if you're not testifying yourself) testify about the decedent and the estate, then sign a sworn 'Proof of Death and Other Facts' affidavit and an affidavit of no debts in front of the court — both confirming, among other things, that the decedent didn't receive Medicaid benefits without a MERP clearance and that no child or spousal support is owed. If the will is self-proved, no outside witness testimony is needed beyond your own. The judge then signs the order.
- 6
Obtain the signed Order Admitting Will to Probate as Muniment of Title
Once the court signs this order, the probated will itself — along with the court's order — becomes the legal record third parties (banks, title companies, county deed records) rely on to recognize the transfer, without a separately appointed executor administering the estate. The order's own text states it gives sufficient legal authority to anyone holding the decedent's property to transfer it to the people named in the will, without further administration.
- 7
Record the order and will where needed (e.g., county real property records) and present it to banks or title companies as required
For real property, the order is typically recorded in the county where the property sits. For financial accounts, present the certified court order and probated will directly to the institution.
- 8
File the follow-up affidavit within 180 days, unless the court waives it
Estates Code § 257.103 requires the applicant to file a sworn affidavit with the court clerk stating which terms of the will have been fulfilled and which haven't, before the 181st day after the order is signed — unless the court waives this or extends the deadline. Put this date on your calendar now: most people forget it once the property has already transferred, and missing it is its own separate problem even though it doesn't undo the transfer itself.
What it actually looks like
Sample pages from the guide
Real pages from the Texas guide PDF. Click any page to enlarge.
-
Cover & key facts
Version, last-reviewed date, the statutory cap, and the disclaimer — all on page 1.
View page -
Table of contents
Every section in the order you'll use it — the eligibility check, the form walkthrough, and the bank-refusal script.
View page -
Plain-English glossary
Key terms translated for a non-attorney reader. The vocabulary the rest of the kit assumes.
View page -
What it does, in plain English
The mechanism explained in plain language, cited to the statute, with your state's exact dollar cap built in.
View page -
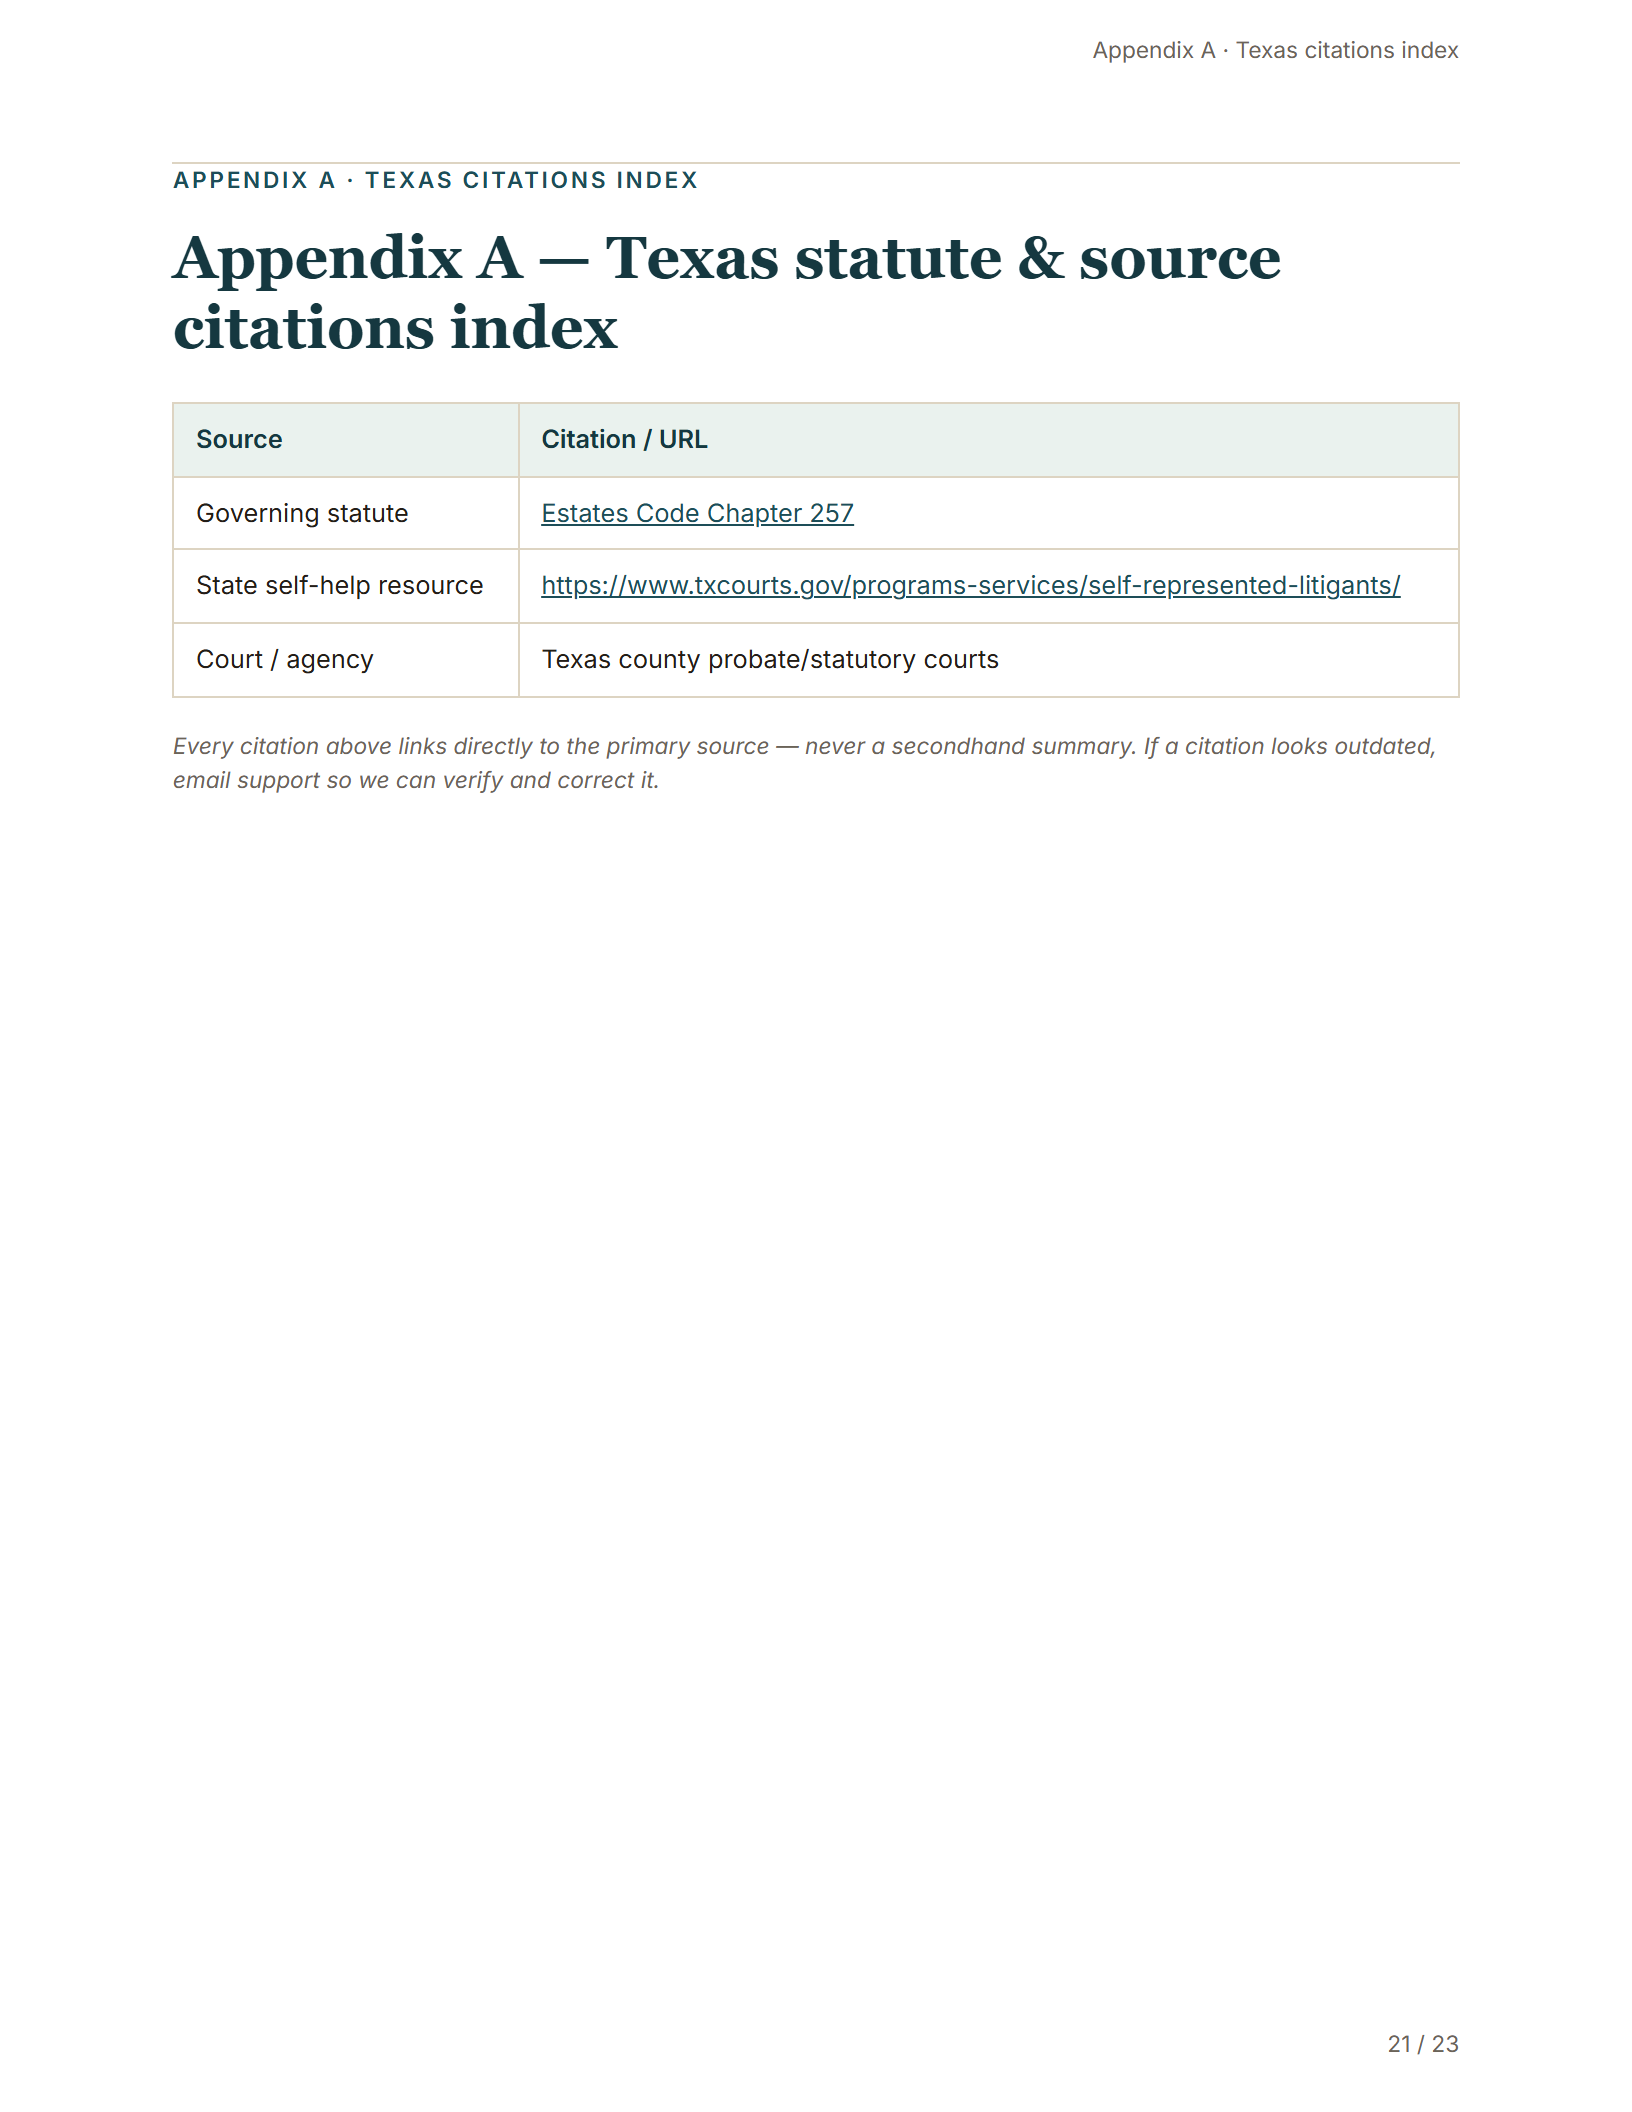
Citations index
Every operational claim sourced to the actual statute or official court/agency publication.
View page
Print-friendly, readable on a phone or tablet, and designed to be taken to the bank or clerk. Every operational claim cites the actual statute or official publication.
How this compares
Texas doesn't publish a fill-in form for this mechanism, so an attorney drafts the filing either way. The $37 is for the guide — the requirements checklist and everything around it — that turns the attorney's job into drafting alone, instead of research-and-drafting on your bill.
| This guide | Attorney alone (no prep) | DIY research, no guide | Doing nothing | |
|---|---|---|---|---|
| Cost | $37 + attorney's drafting fee | $1,500–3,500 (research + drafting) | $0 upfront — real risk of a rejected filing | Eventually full probate, if the estate is never settled |
| Time to filed | Faster — drafting only | 2–6 weeks (research + drafting) | Unpredictable | Not until you act |
| Bank/DMV/clerk pushback script | Yes | Sometimes | No | n/a |
| Statute citations | Yes | n/a | If you find them yourself | n/a |
| Delivery time | Instant (guide); attorney schedules separately | After consult + retainer | Instant, but unverified | n/a |
Attorney costs reflect typical Texas probate-attorney retainers for this kind of filing.
The most-searched sticking point
What to do when a bank, DMV, or clerk pushes back
A facially valid filing still gets rejected on the first try more often than it should — usually because front-line staff have never processed one before, not because anything is actually wrong. This is the single biggest gap in every free state resource: none of them tell you what to actually say. The guide's Section 5 gives you the exact script and citation for each of these:
- Bank insists on court-issued Letters Testamentary before releasing funds
- Title company asks for a full inventory of the decedent's assets before insuring a sale or refinance
- The estate involves out-of-state investment accounts or brokerages
Each one has a specific script and statutory citation behind it — not just "you're right, they're wrong," but exactly what to say and what document to hand over. That's in the guide.
If a bank, DMV, title company, or court clerk rejects your filing for a reason traceable to following this guide, you get a full refund.
Email the stated rejection reason to support@estateaffidavitguide.com within 30 days of purchase and we refund the full purchase price within one business day. No phone tag, no forms, no fight. Not covered: an estate that turns out to be over the dollar limit, a dispute among heirs, or a missing document unrelated to the filing itself. Changed your mind for any other reason? You have 7 days, no questions asked. Full refund policy.
Avoid these
4 common reasons filings get rejected
No valid will exists
The estate has unpaid debts other than a home-secured lien
More than four years have passed since the date of death
Undisclosed Medicaid benefits or unresolved support obligations
Before you present the Texas Muniment of Title
Most rejected-on-the-first-try filings are a front-line-staff problem, not an eligibility problem. This free one-pager has what to bring and what to say the first time you hand it to a bank, DMV, or clerk — emailed now. We'll also send a few short follow-ups over the next few weeks (why most pushback is unfamiliarity not law, the exact citation to point to, when to call an attorney) — then we stop. No ongoing newsletter.
Questions
Frequently asked questions
What's the difference between Muniment of Title and the Small Estate Affidavit in Texas?
Do you need a lawyer to file for Muniment of Title in Texas?
Can Muniment of Title be used more than four years after death?
What happens to the mortgage on an inherited house?
Does a Muniment of Title filing need to go to a bank the way a Small Estate Affidavit does?
Which Texas mechanism applies to my situation — Small Estate Affidavit, Muniment of Title, or Affidavit of Heirship?
We missed the 4-year deadline for Muniment of Title — do we have any options left?
Ready to start?
$37, one time. Instant download. Money-back if your filing is rejected for a reason traceable to following the guide, or for any other reason within 7 days.
No waiting room, no retainer. Most of the remaining delay families hit is an avoidable rejection or a second trip back to the same bank, DMV, or clerk — this guide is built to help you avoid both on the first visit.
One last step — confirm below and it's instant from there.
Secure checkout by Stripe · Instant download · Money-back guarantee
Want a sibling or co-executor caught up? Send them what you just read.
Not ready to buy yet?
5 short, plain-English emails over the following weeks — the eligibility math, the muniment of title presentation moment, why most rejections are paperwork not eligibility, and when to call an attorney instead. Then we stop. No ongoing newsletter, no sales list. Unsubscribe anytime.
Primary sources
State sources
Every claim here cites the actual statute or an official publication — see them
- Statute: Estates Code Chapter 257 . The primary source behind every requirement, cap, and deadline described above.
- State self-help resource: Texas county probate/statutory courts